Can a 2% Levy Fix France’s Deficit, Without Losing Its Billionaires? The richest man in Europe, Bernard Arnault, says NO!
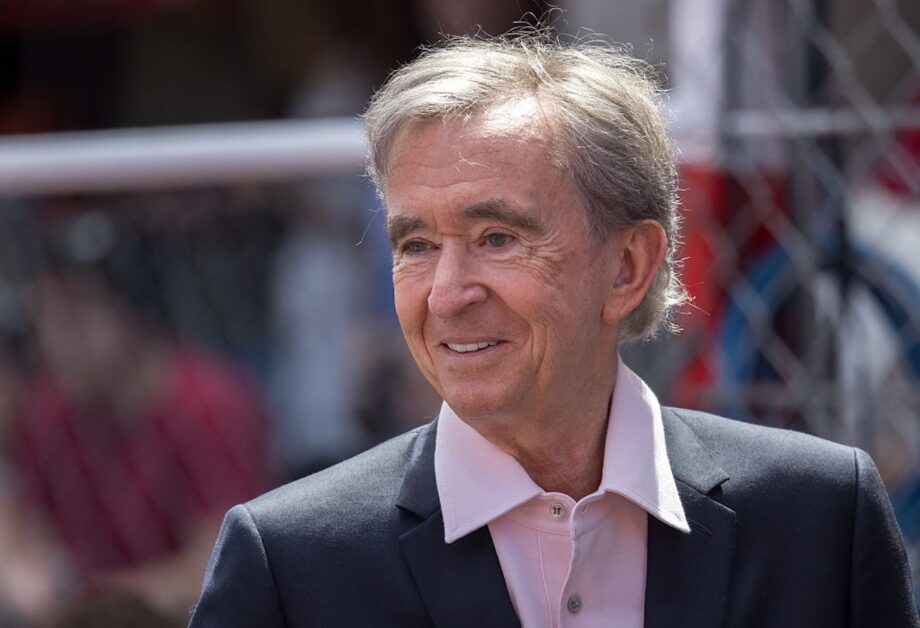
France has been here before: a government searching the sofa cushions for savings, a restive public eyeing the wealthy, and a famous billionaire warning that a new levy will drive success out of the country. This time, the flashpoint is a proposed 2% annual tax on fortunes above €100 million, instantly branded the “Zucman tax,” after the Paris-based economist who helped design it, and the loudest critic is Bernard Arnault, the luxury magnate whose conglomerate, LVMH, has become a shorthand for French soft power.
Arnault did not bother with euphemism. In a weekend statement that ricocheted through the political class, he cast the plan as an attack on the market economy and a mortal threat to growth. The CEO of luxury group LVMH, said that a proposed 2% levy on France’s wealthiest citizens, those with assets worth more than €100 million, is “an offensive that is deadly for our economy”.
Bernard Arnault, once the world’s richest person, has a fortune estimated to be worth $157.1bn (€133.5bn), according to Forbes. So, this was a calculated intervention from a man who personifies French corporate dominance abroad and who, not so long ago, triggered a national row by flirting with Belgian citizenship. His point now is as simple as it is controversial: tax the ultra-rich on their stockpiles of wealth, and they will leave, or at least invest less, leaving the state poorer, not richer.
The proposal lands at a precarious moment. France’s budget deficit is among the eurozone’s highest and public debt has climbed into the triple digits as a share of GDP. Austerity just toppled one prime minister; Sébastien Lecornu, newly installed at Matignon, inherits an arithmetic problem with political teeth. A sweeping package of spending cuts failed to survive the National Assembly. Raising broad-based taxes risks bruising an electorate already squeezed by living costs. That leaves the richest sliver, roughly 1,800 households, by one estimate, squarely in the crosshairs.
Supporters of the levy present it as a matter of fiscal realism and democratic hygiene. Wealth at the very top has soared over the past decade, they argue, while taxable income can be minimized with ease in a world of holdings, trusts and paper losses. A light skim on extreme balance sheets, they say, could produce a meaningful annual haul for the Treasury, money that might steady the country’s credit rating, protect public services, or finance the green transition. To them, the billionaire backlash only confirms the reform’s necessity.
Critics see a different ledger. A mark-to-market wealth tax is administratively thorny and politically seductive, a formula, they warn, for disappointment. Asset values swing; liquidity is uneven; and valuation fights are magnets for litigation. The larger fear is behavioral: even a small annual charge, applied relentlessly, may nudge founders, heirs and fund managers to redomicile, re-register or simply rethink where future factories, studios and headquarters should land. All of this is more than rhetoric in a country that scrapped a broad wealth tax in 2018 after decades of debate about capital flight.
The stakes extend far beyond a handful of gilded postcodes in Paris. LVMH and its peers anchor a supply chain that runs through workshops in Lyon and perfumers in Grasse, ad agencies in Boulogne-Billancourt and glassmakers in the Vosges. France’s equity market is unusually concentrated in global luxury and consumer champions; its export strength and stock index both reflect that concentration. A policy that antagonizes the sector’s figurehead, defenders of the status quo say, risks denting a brand that punches well above its demographic weight.
Yet politics rarely pauses for corporate sensitivities. The opposition on the left is newly energized by the prospect of “fiscal justice” after months of battles over spending restraint. Green and Socialist leaders want the wealth levy folded into the next budget. The far right is hedging, wary of alienating voters who like the idea and donors who do not. And, at the end of the day, public opinion appears to favor the concept overwhelmingly. In a fragmented Assembly, this odd coalition of pressure could prove more durable than it looks at first glance.
France has tools to make a wealth tax smarter than its predecessors: carve-outs for productive investment, credits for equity in domestic ventures, smoothing mechanisms for volatility, guardrails to avoid cash-flow squeezes on family firms. None of that resolves the core choice the country faces. Either the state leans more on those who own the biggest pools of assets, or it leans harder on everyone else, with spending cuts, broader taxes, or both. Pretending the arithmetic can be wished away is how governments fall.
Arnault’s warning and the Zucman camp’s rejoinder bookend a debate that is ultimately about strategy. Can France shore up its finances without dimming the dynamism that gives it leverage in the world economy? Can it signal seriousness about inequality without scaring off the very investment that funds pensions, hospitals and universities? The answers will shape not only next year’s budget, but the country’s social settlement for years to come.
What is certain is that the argument won’t be settled by one statement from a billionaire or one clever proposal from a scholar. It will be decided in committee rooms and conference calls, in bond markets and factory towns, and by whether a government that has already lost one vote can persuade a wary public that solvency and ambition need not be opposing ideas.
By I. Constantin