EU – China commercial agreement. Brussels preparing new pressure tools without seeking a breakdown in relations.
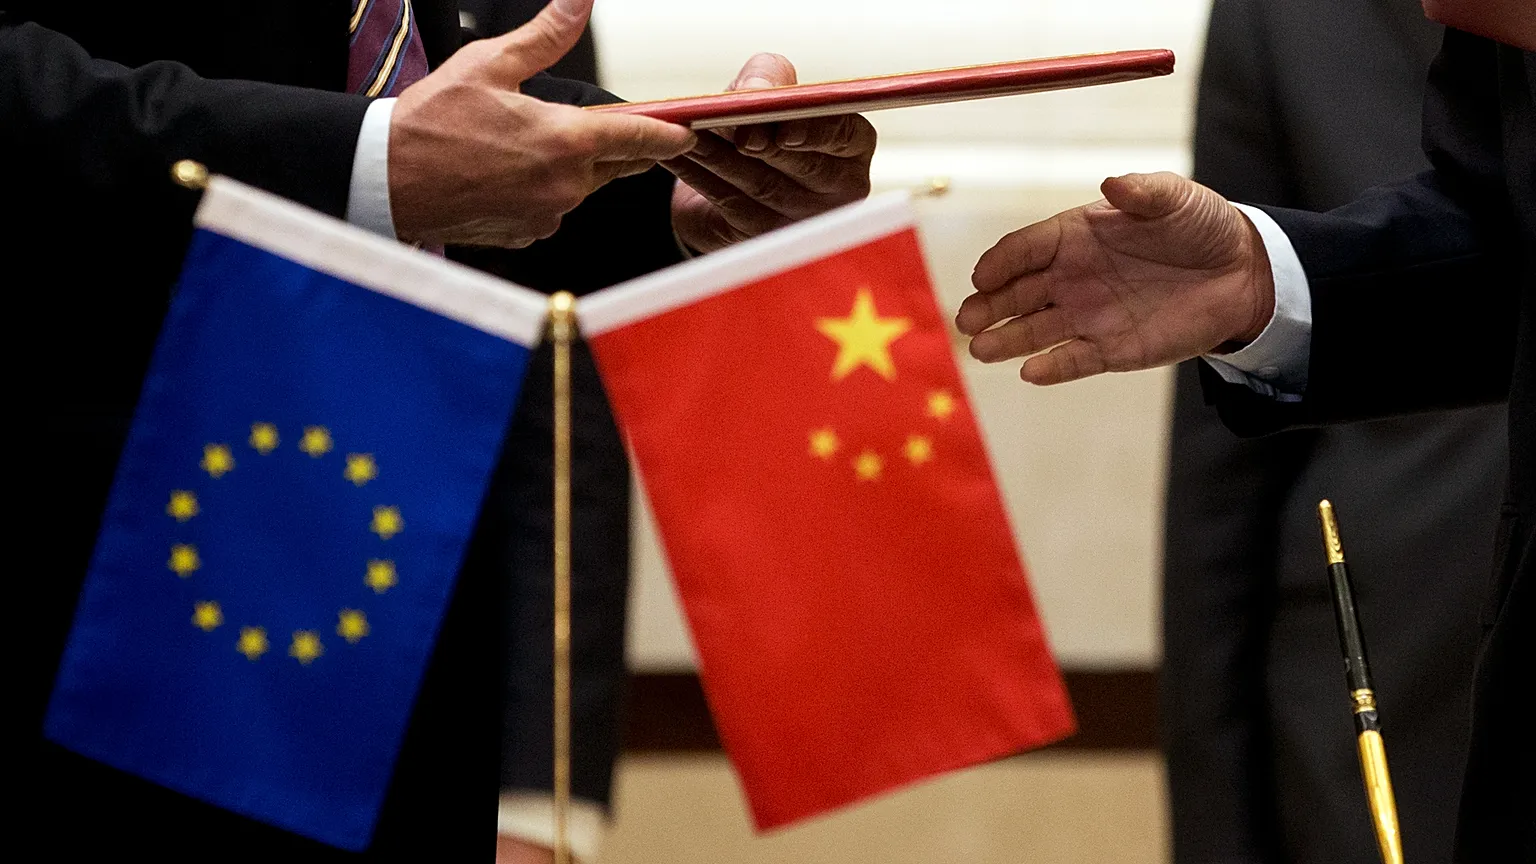
For months now, within the European Union, discussions have been underway regarding the possibility of limiting imports of Chinese products, particularly in the automotive sector, to counter the sales crisis facing all of Europe, particularly Germany, Europe’s historic economic powerhouse.
A complete trade disruption remains unlikely, while targeted measures against China’s excess production capacity are becoming more concrete. Investors will be particularly concerned about the most exposed sectors and supply chains. The trade war between Europe and China is entering a more delicate phase, with Brussels preparing new pressure tools without seeking, at least for now, a breakdown in relations. European Commission President Ursula von der Leyen’s State of the Union address adopted a more conciliatory tone toward China than expected, reinforcing the possibility of an approach based on targeted pressure, rather than a breakdown, ahead of the next round of trade negotiations. Trade relations between Europe and China are approaching a more contentious phase. However, investors should not confuse the escalation with the imminence of a trade war. A “Liberation Day”-style approach, characterized by the introduction of aggressive, broad-based tariffs on large portions of trade, remains unlikely in the EU-China context.
Brussels has good reasons to intervene. The EU’s trade deficit with China has widened significantly since the pandemic, and all member states now run a trade deficit with China. In 2025, China’s trade surplus with the EU reached €360.6 billion, according to data cited by the European Commission, and is expected to widen by a further 9% in the first half of 2026.¹ Rising Chinese imports have been accompanied by a decline in EU exports, with particularly marked effects in Germany, where imports from China have increased significantly in the electrical equipment, computer, electronics, and optical products sectors, while exports of machinery and motor vehicles have declined. In fact, German industrial production in sectors most exposed to Chinese competition has declined significantly compared to less exposed sectors.
China’s export basket has become progressively more similar to Europe’s, and the export similarity index between the two economies has increased over the past two decades. This means that EU exporters are increasingly competing directly with Chinese companies in third markets, rather than simply importing products from China. Sectors such as machinery and equipment, metals, chemicals, and automotive now have the greatest degree of overlap and the greatest price pressures. This shift defines the contours of the problem. A widening trade deficit caused by cheaper imports can be managed through border tariffs. However, a growing gap caused by the replacement of European companies by Chinese firms in global markets cannot be addressed in the same way, prompting the authorities in Brussels to explore broader industrial policy solutions.
Brussels has effectively concluded that the tools currently available are inadequate to address the scale of the problem. Antidumping measures are slow and often subject to circumvention, while safeguard measures, which can be applied rapidly to entire product categories, have historically suffered from a lack of convergence within European industry. From China’s perspective, Europe is too important a market for Beijing to risk provoking a reaction without careful consideration, especially given that its share of exports to the United States continues to decline. It is therefore likely that, at least initially, the tools at China’s disposal will be used reactively rather than for escalation.
This dispute is part of a broader context of global trade fragmentation. Internationally, there is limited consensus on how to respond to China’s industrial model, with governments adopting differing approaches. For example, while the EU and the International Monetary Fund have supported a rebalancing of China’s subsidy-consumption mix, the United States has placed greater emphasis on currency adjustment.
The main constraint on more aggressive action is the reality of economic interdependence. China maintains significant escalation capacity through its role in supply chains of critical goods and components and in the provision of strategic inputs, limiting Europe’s ability to impose blanket trade restrictions. The nature of the trade relationship has also changed: access to the Chinese consumer is less important than in the past, while the resilience of supply chains takes on greater importance. Europe will strengthen its negotiating position without triggering supply disruptions that could harm its own producers.
After two days of talks in Beijing, the European Union and China have reached an agreement that could reduce Chinese exports of hybrid and plug-in hybrid cars by more than half over the next four years, preventing the arrival of several million vehicles. The announcement came on Friday from European Trade Commissioner Maros Sefcovic, at the end of talks with Chinese Commerce Minister Wang Wentao, ahead of the European leaders’ summit next Thursday in Brussels.
The agreement, described as a first step toward rebalancing a trade deficit exceeding €1 billion a day, also includes Chinese tariff reductions on approximately €4 billion of European exports and licensing facilitations for rare earths and permanent magnets. In addition to cars, the two sides reached agreements on other fronts. China agreed to reduce import duties on approximately €4 billion of European products, including auto parts, olive oil, and footwear, resulting in estimated savings of €225 million for exporters, according to the Financial Times.
Regarding rare earths and permanent magnets, Beijing has pledged to continue facilitating the issuance of export licenses to the EU through a “fast track” or green channel mechanism, a factor highlighted by the Chinese Ministry of Commerce and reported by Le Monde. The overall agreement includes 16 points of consensus, according to the Chinese ministry cited by CNBC, and also includes explorations of market access for medical devices in China and the easing of some health measures restricting European meat and livestock exports.
The two sides will continue to discuss price undertakings as an alternative to tariffs and will meet again via video conference in January and in person in March 2027.
By Domenico Greco